
Transformation · Insurance
Where to place the next agent, decided before recruiting starts.
One of India's largest life insurers was expanding its agency channel with no view of which micro-markets to enter. Every market was classified by growth potential, and policyholder clusters with no agent nearby were surfaced separately.
Large life insurer
Agency channel
Tier 3–5 markets
What the engagement delivered
The situation
The agency channel is this insurer's largest distribution engine, and the next phase of growth sits in Tier 2–5 markets. Getting advisors into the right places ahead of competitors is the whole game.
Unit Managers were being directed to recruit, but given no view of which villages, PIN codes or micro-markets to enter. Scouting was manual, three to five days per market, and the quality of the result varied with the individual doing it.
Four gaps between recruitment and opportunity
01
Recruiting without a map
Unit Managers were told to hire, but not where. Target markets were chosen from local familiarity.
02
New agents placed conveniently
Recruits landed in accessible geographies rather than high-opportunity ones. Ramp time was lost from day one.
03
Active agents beside
untapped markets
Productive advisors were working exhausted micro-markets while high-opportunity clusters sat adjacent, unnoticed.
04
Policyholders beyond reach
Customers living far from any active agent received little servicing. Lapse rates followed.
Why a population map isn't enough
Three things decide agency performance that a demographic view does not capture.
Population is a weak proxy
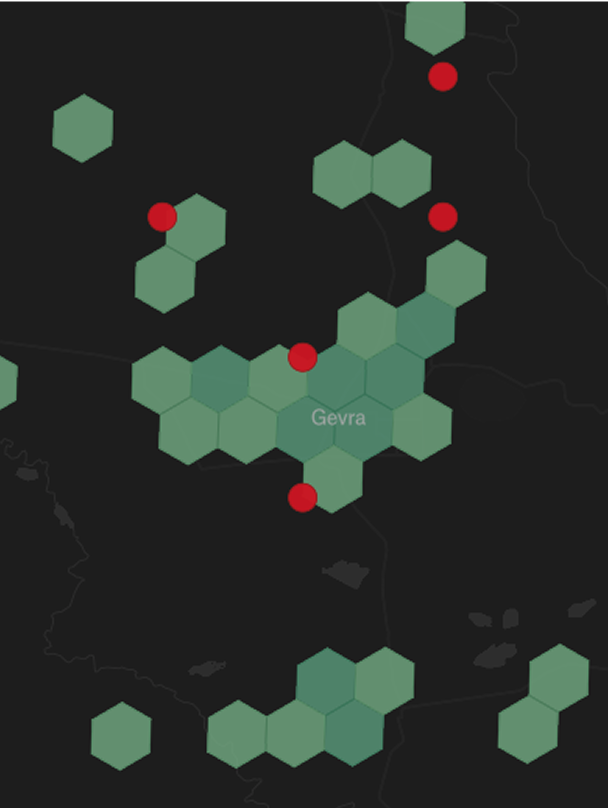
Two markets of identical size can carry entirely different insurance propensity. Wealth signals, formalisation, MSME density and consumer durable presence separate them; head count does not.
Presence is not penetration
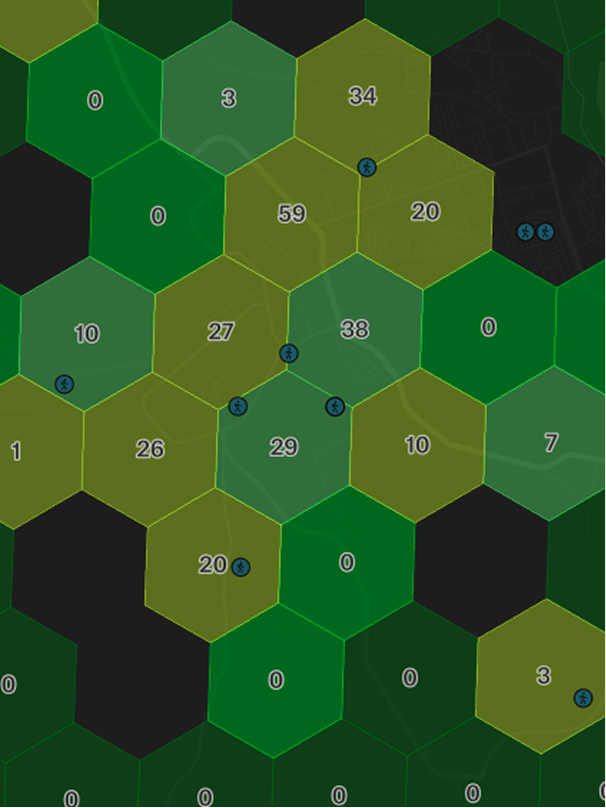
Having agents in a market says nothing about how much of it has been captured. Well-covered markets can be exhausted; thinly covered ones can be wide open.
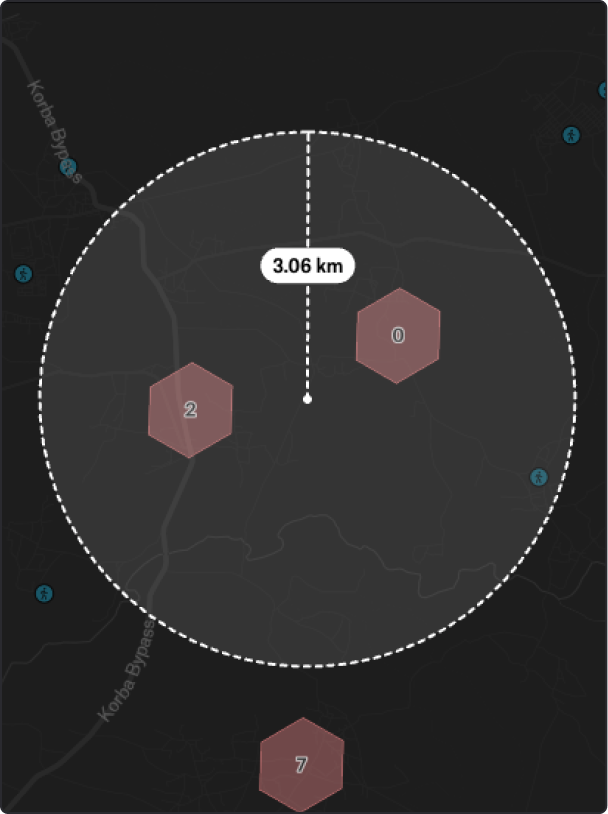
Distance decides retention
Acquisition gets the attention; servicing distance drives the lapses. A policyholder with no agent nearby is a renewal already at risk.
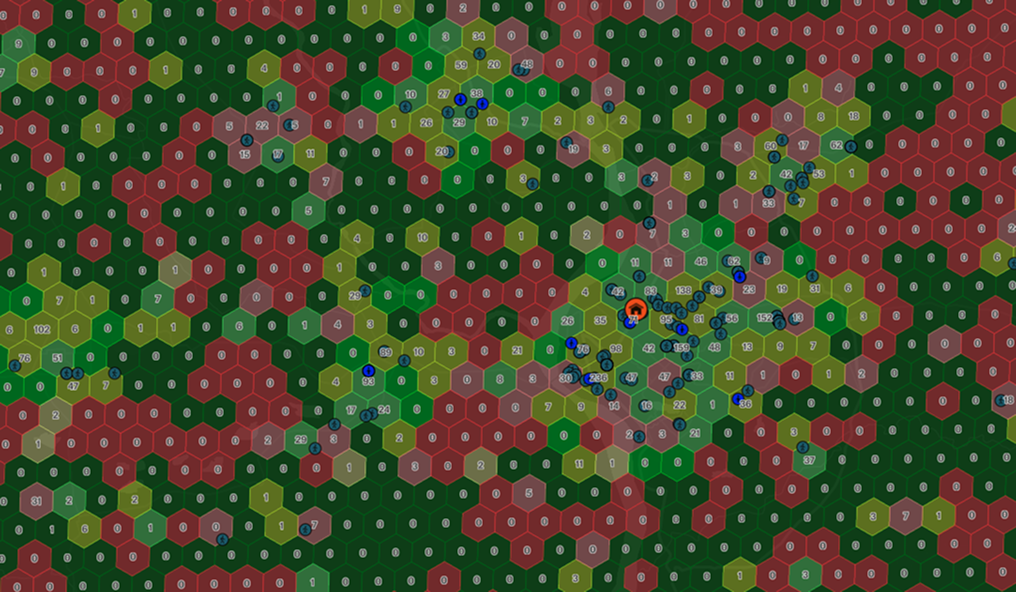
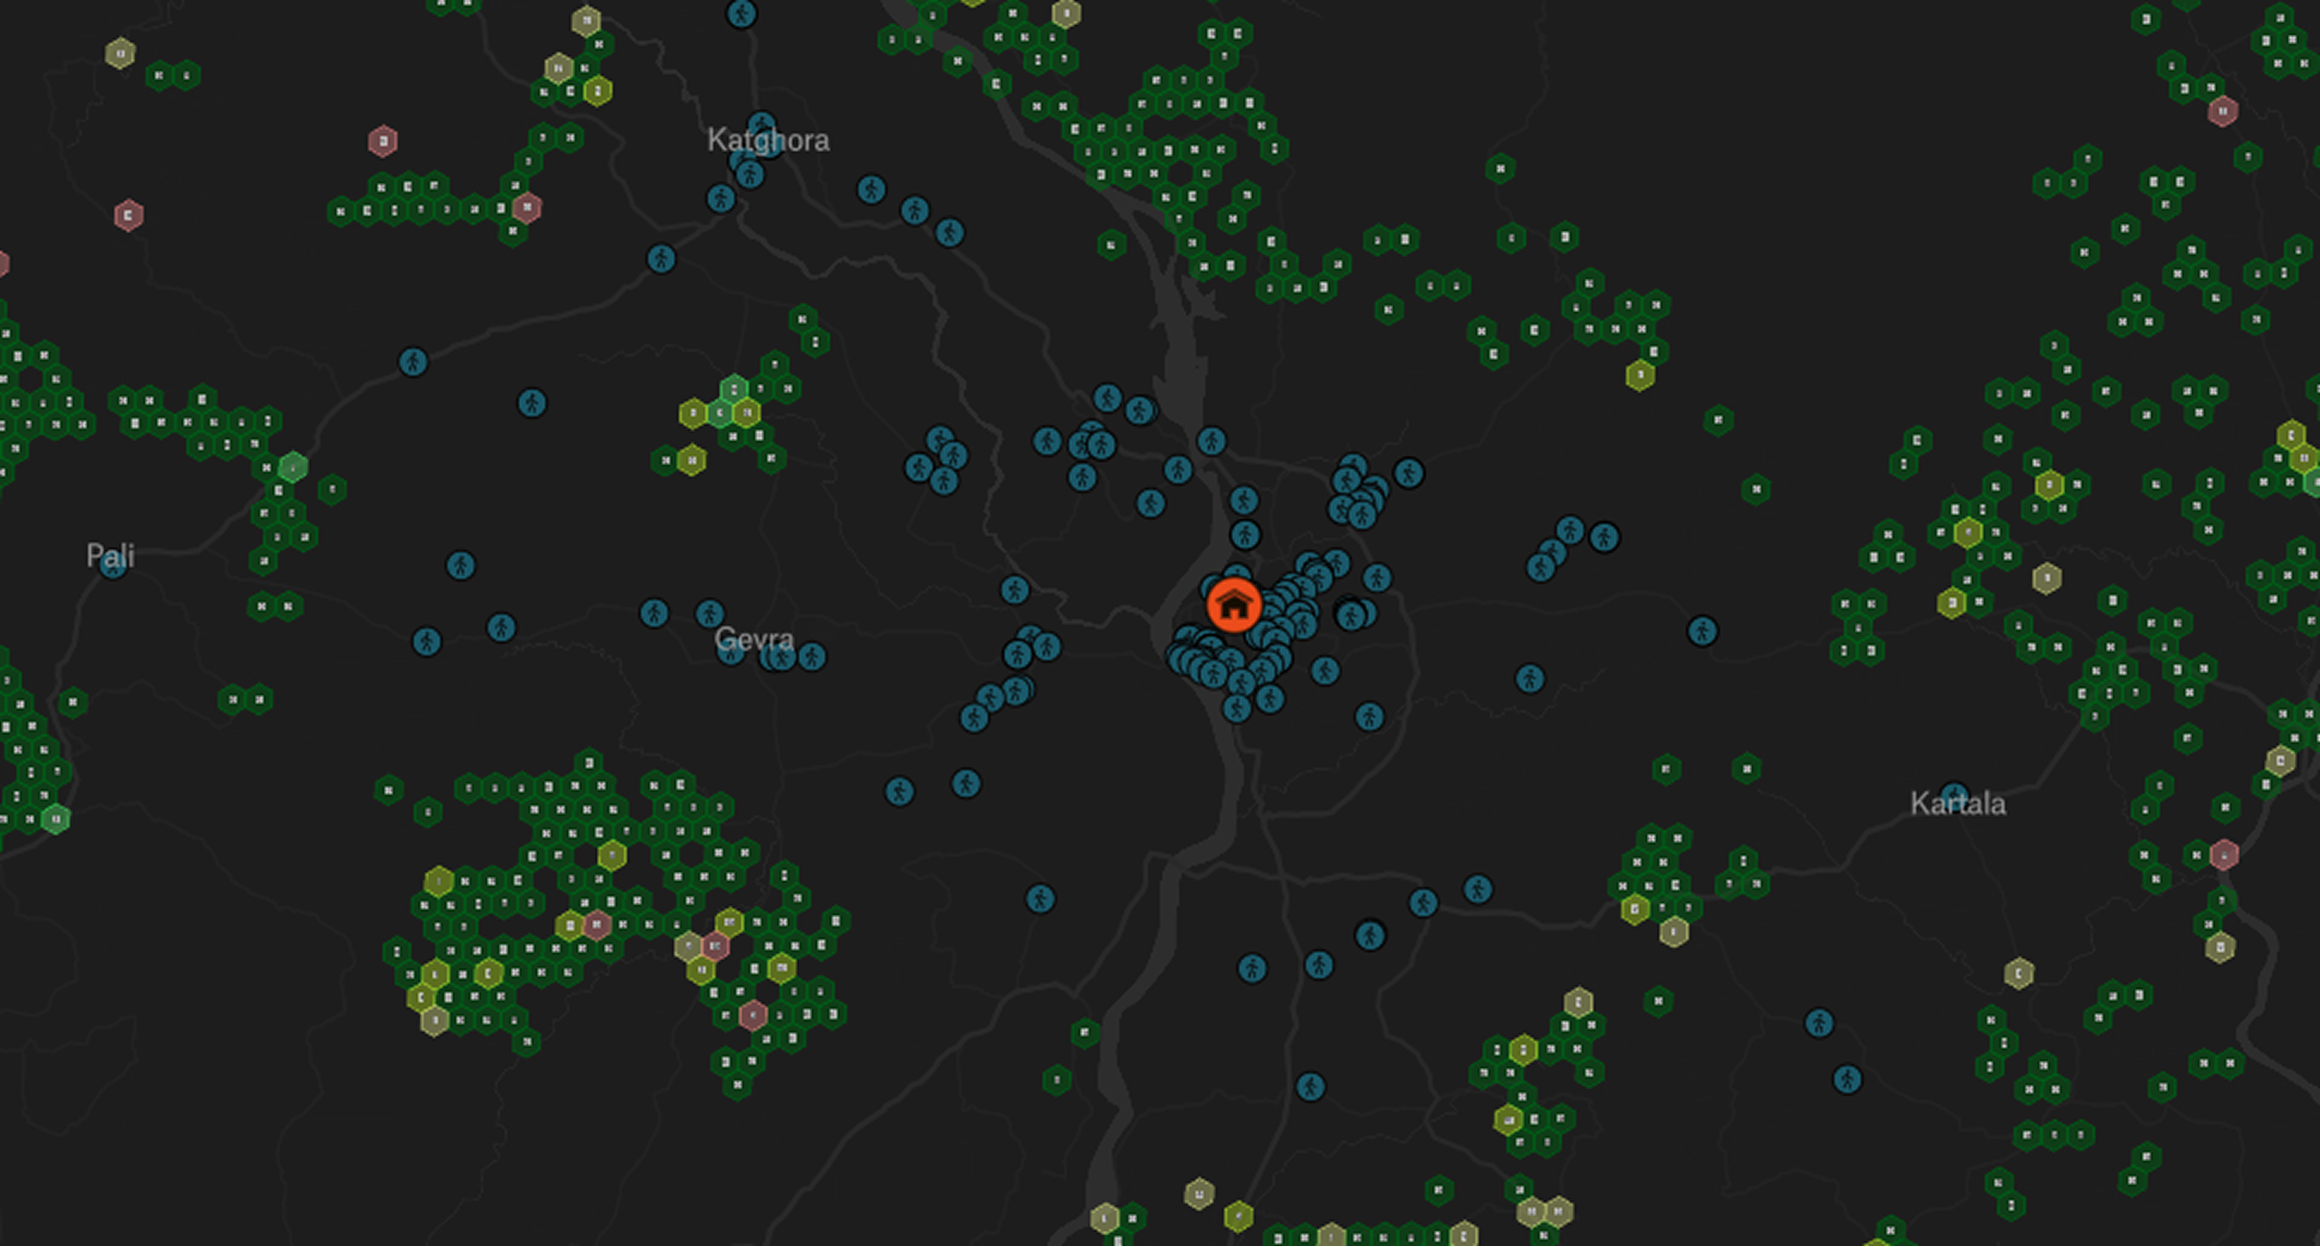
Every market, classified into one of five zones
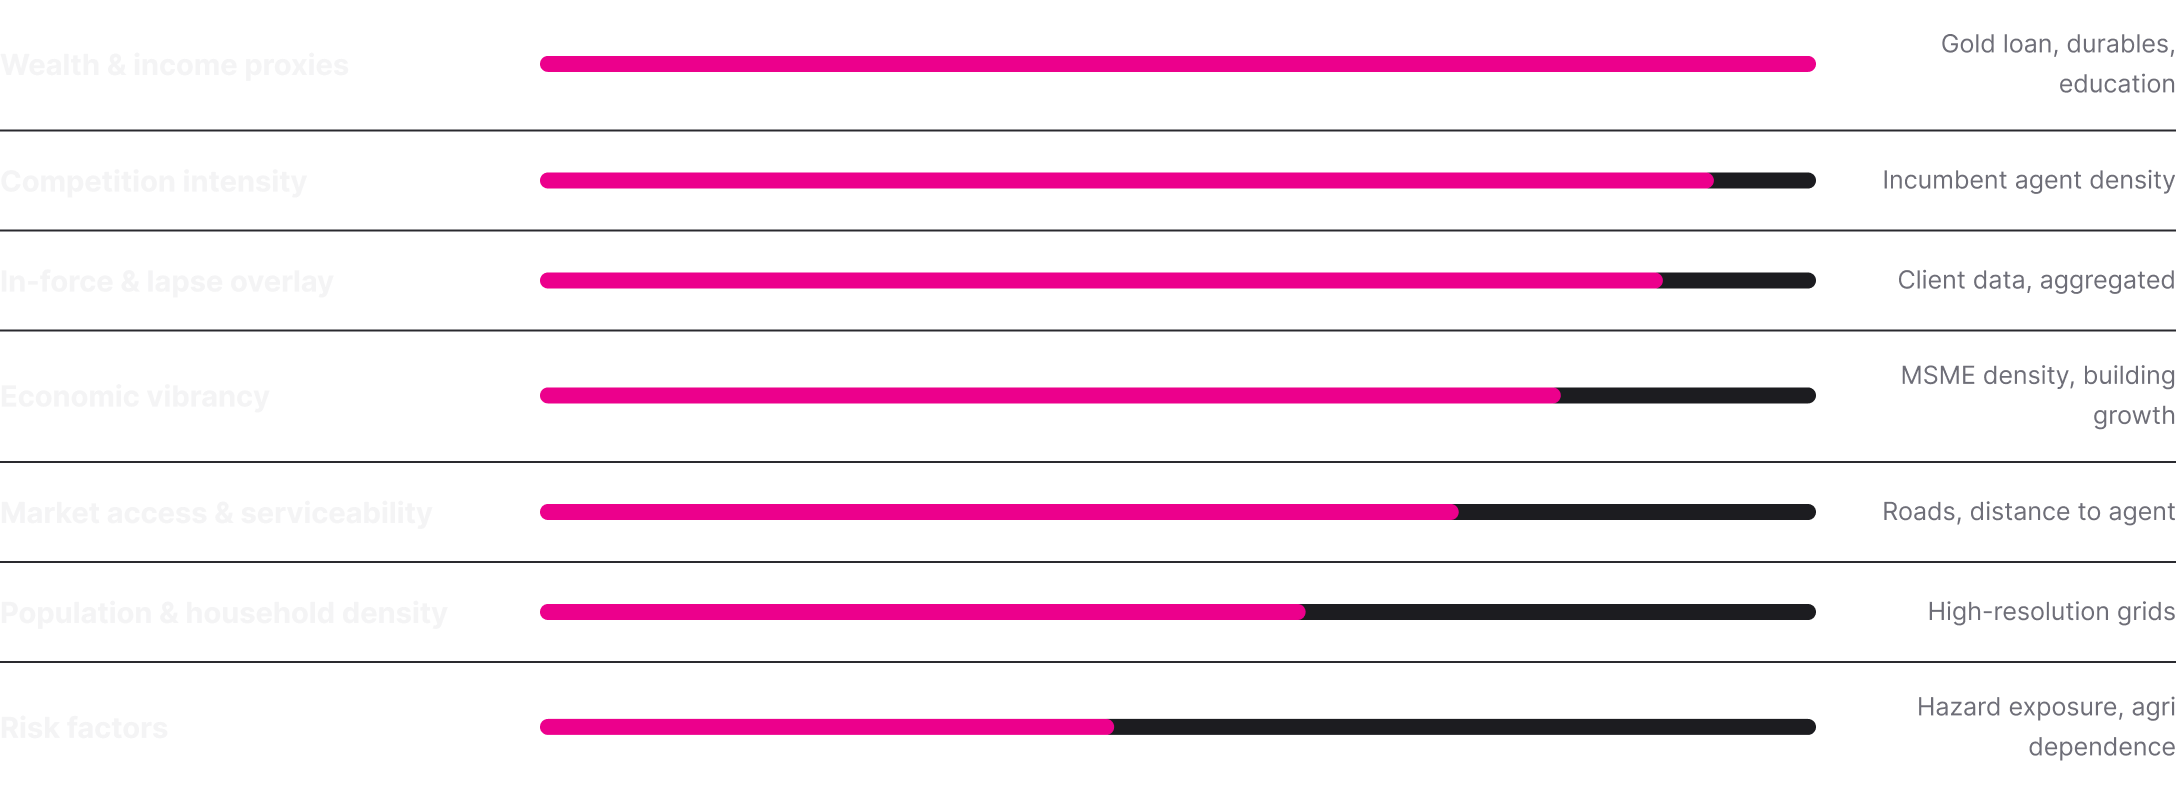
Built by layering wealth and income proxies, population, competitor agent density, serviceability, and the insurer's own in-force and lapse data. Each zone carries a different instruction.
Priority White Space
Zone 01
High opportunity and wealth potential, low market penetration. The market is there; the insurer isn't.
Action
Recruit here first
High Yield Markets
Zone 02
Strong existing presence with proven agent productivity and growing revenue.
Action
Protect and deepen
Stable Markets
Zone 03
Well-penetrated territories with steady renewals and consistent retention.
Limited headroom.
Action
Maintain, don't over-invest
Quality Review Zones
Zone 04
High policy lapse rates alongside slowing growth. Something is wrong that recruiting will not fix.
Action
Operational branch review
Service-Starved
Catchments
Zone 05
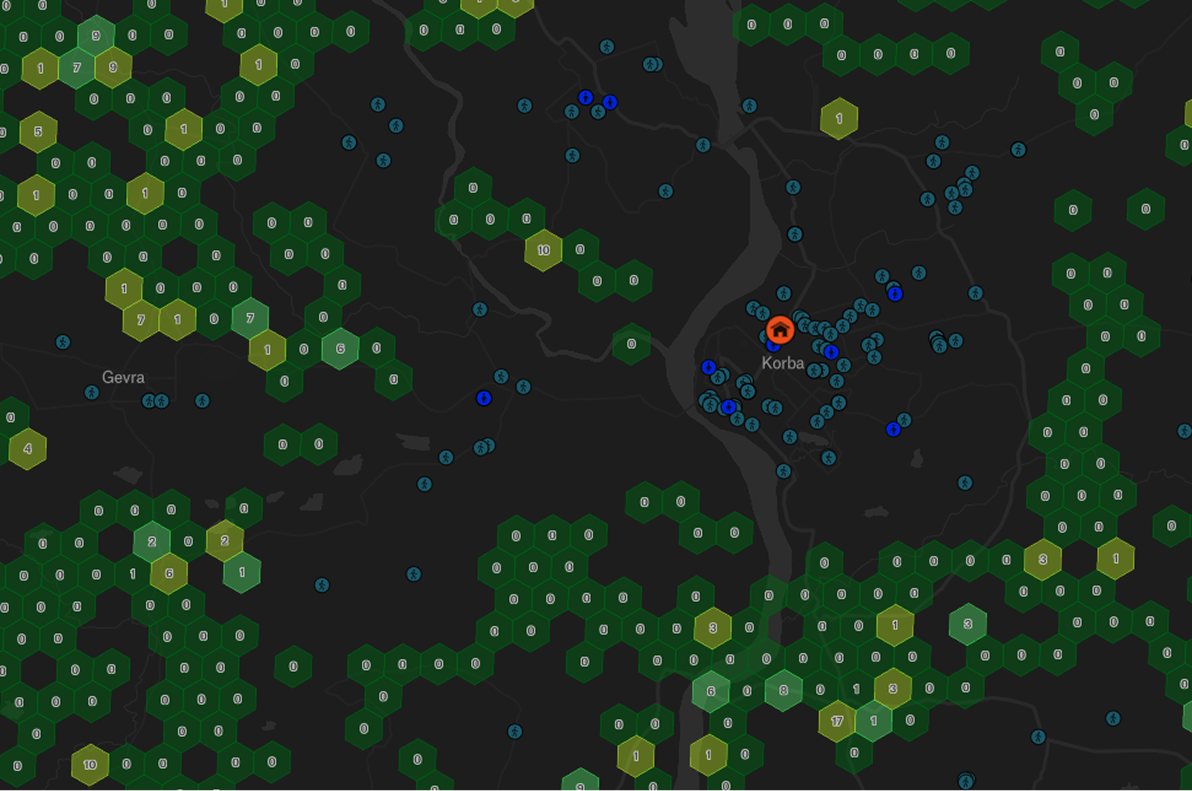
High customer density where the nearest servicing agent is more than five kilometres away.
Action
Recruit locally, into the pocket
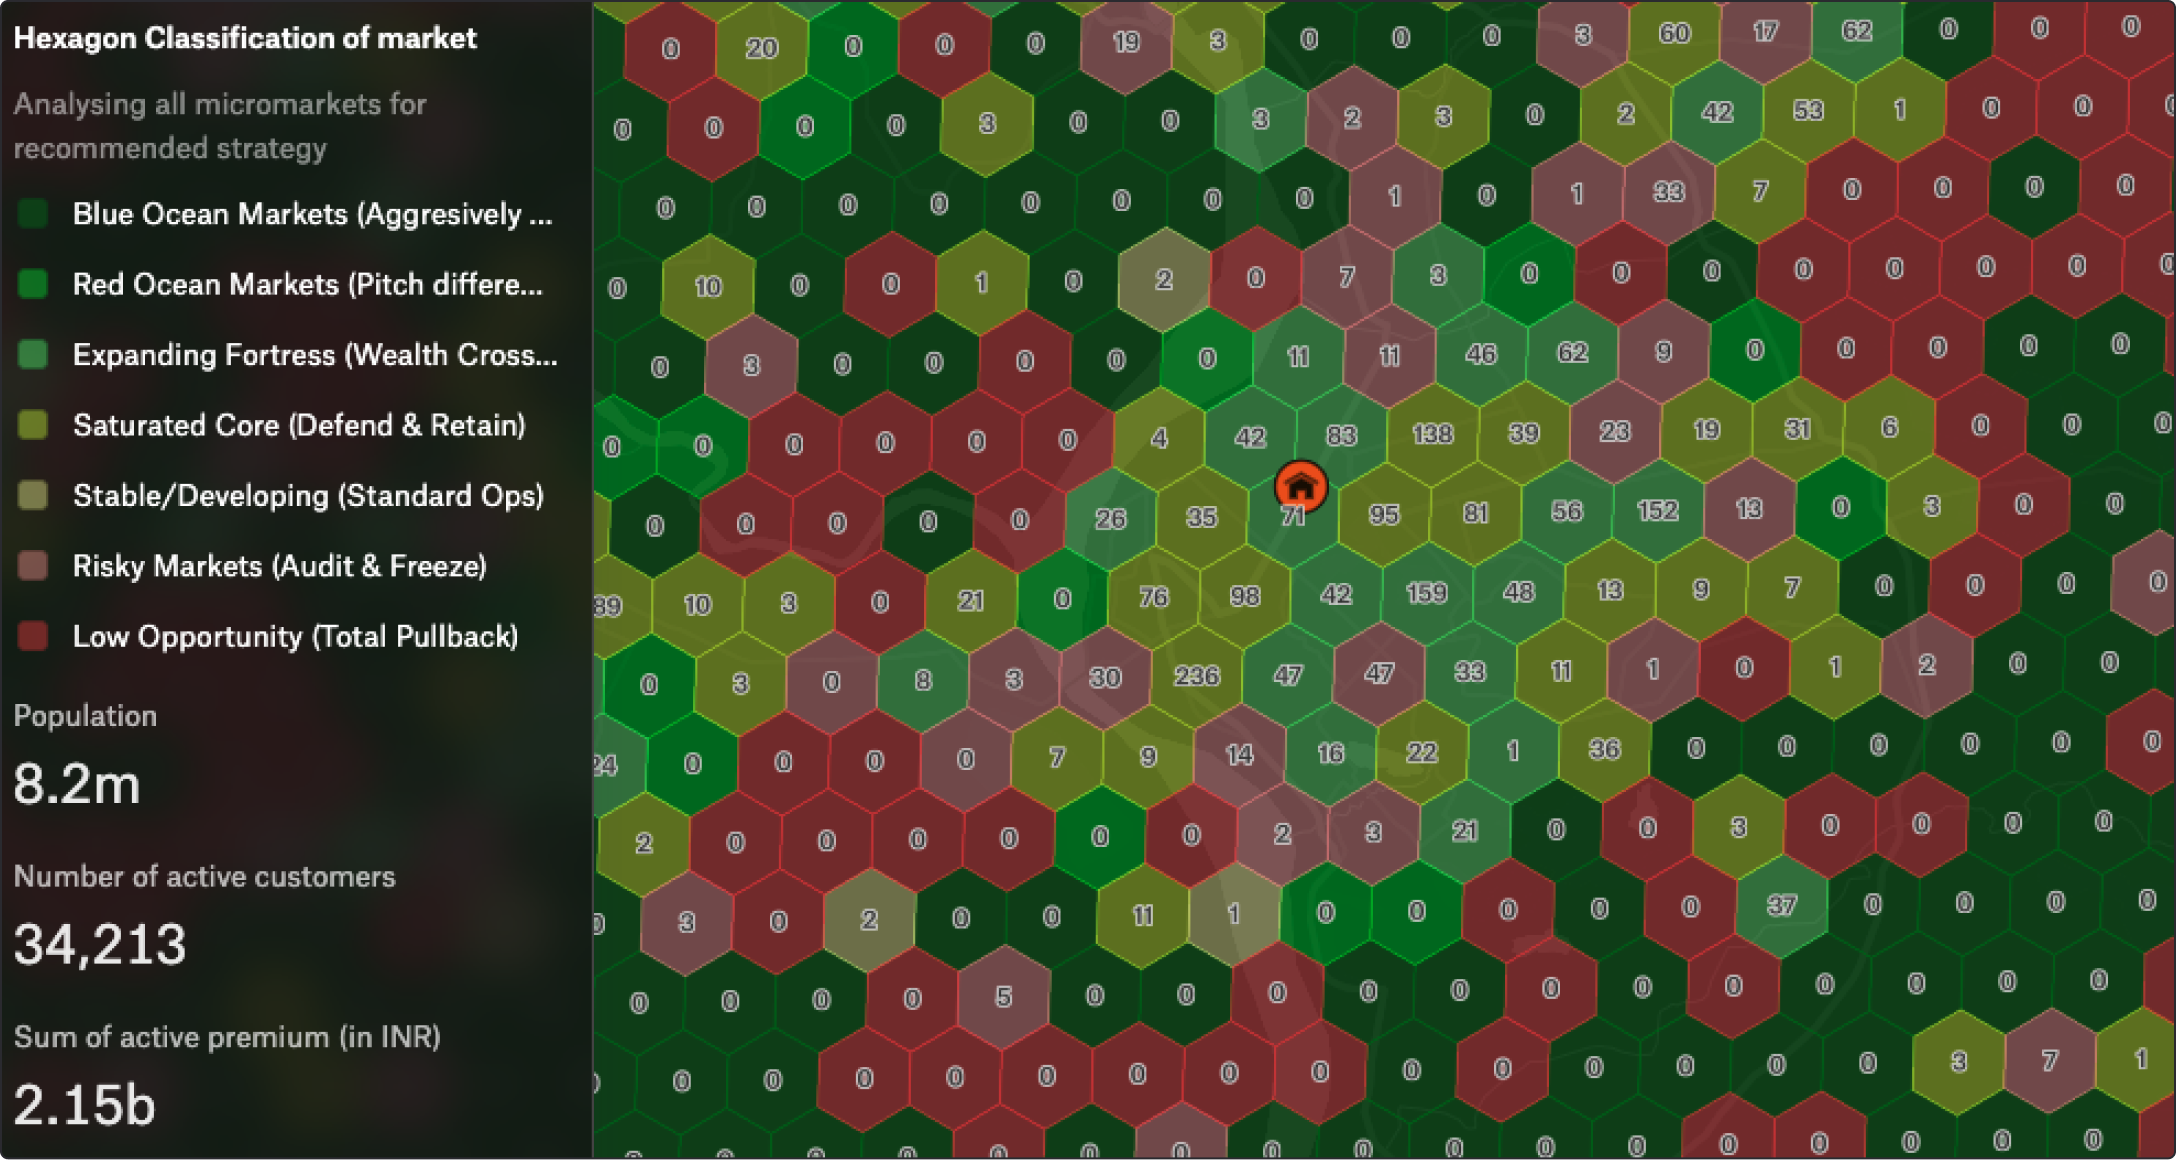
The five-kilometre problem
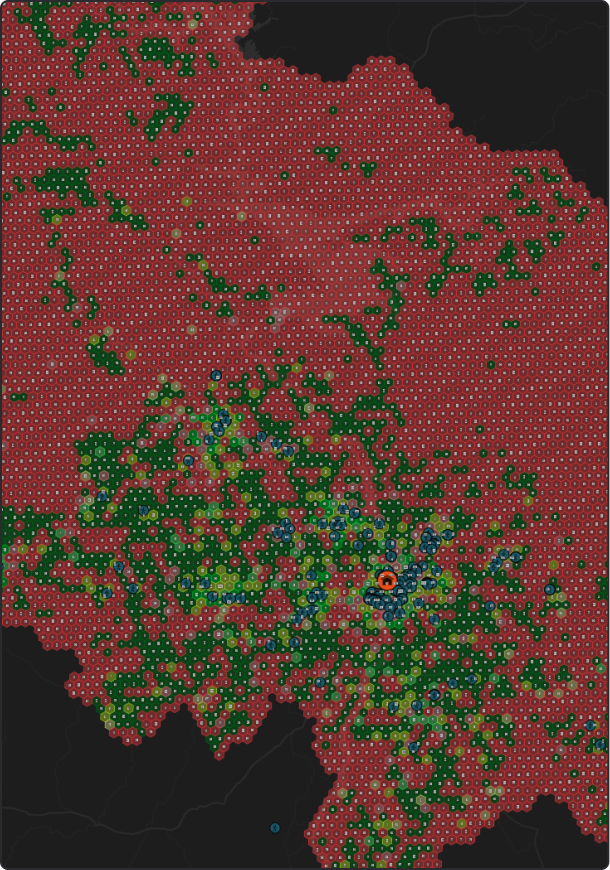
Servicing quality falls away with distance, and lapses follow. Branch leaders can filter directly for dense policyholder clusters with no agent inside the radius, then recruit into those pockets.
Beyond 5 km
No agent in range. Servicing drops away and
lapse risk concentrates.
The action
Isolate the cluster, recruit a local advisor
directly into it.
Within 5 km
Active agent present. Servicing is routine,
renewals hold.
What feeds the classification
Public and licensed signals, combined with the insurer's own anonymised portfolio view.
What each team received
One output per role. Field teams get a list, not a map to interpret.
Leadership
A live territory review
Zone classification across the footprint, with lapse concentration and coverage gaps visible by region, built for monthly territory reviews rather than annual planning.
Unit Managers
A recruitment brief
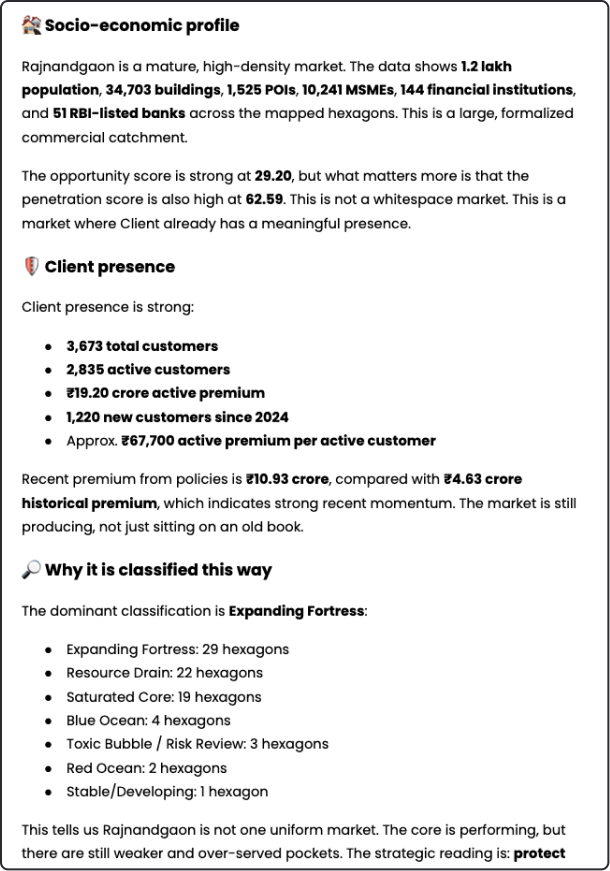
Ranked white-space markets, named prospect businesses to approach, and a placement gapmap showing where managers currently sit against where the opportunity is.
Field
A filterable list
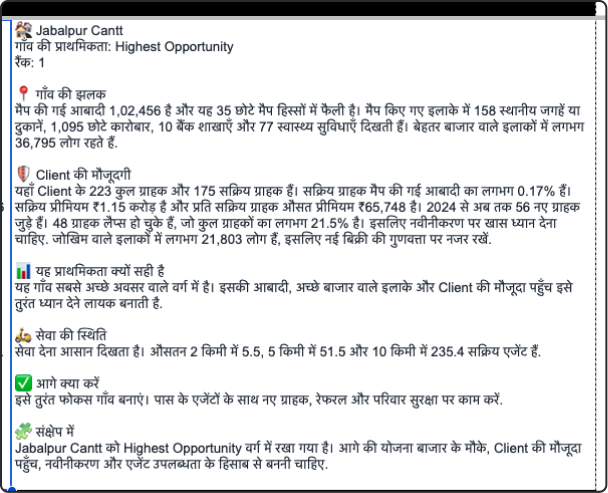
Named locations at PIN code and village level, filterable on the criteria that matter, for example population above 50,000 with fewer than five agents present. Exportable, not a map to decode.
How the workflow changed
Before
Unit Managers chose markets from local familiarity
Three to five days of manual scouting per market
New agents placed where access was easiest
Lapse concentration invisible until the renewal missed
Territory reviews ran on aggregate branch numbers

After
Markets ranked and classified before recruiting begins
Scouting replaced by a ready brief with named prospects
Agents placed into identified white space from day one
Service-starved catchments surfaced and staffed deliberately
Reviews run on a live map, at micro-market resolution
How it was built and proven
The classification was built against the insurer's own in-force and lapse data, so every zone was tested against outcomes the business already recognised. Where the model said a market was exhausted, the renewal data agreed.
Version one delivers a one-time intelligence snapshot across the footprint. Version two adds a custom life insurance propensity model calibrated to the agency channel's product mix, with weekly insights. Version three closes the loop between field activity and market intelligence.
How the engagement was held to account
01
Tested against the insurer's own portfolio. Zones were validated against in-force and lapse performance the business already had, not against an external benchmark.
02
Aggregated data only. Portfolio signals were used at market level. No personally identifiable customer information was required or held.
03
Every recommendation carries its reason. Field teams can see why a market ranked, and challenge it on the ground.
We want this map to ask them to go to the exact specific areas where they can recruit more agents, and we want to tell them why, and in the simplest possible format.
The map is a leadership tool. What reaches the field is a filtered, exportable list of named locations with a recruitment target attached to each one, usable on a phone, with no training required.
Run this on one of your regions.
Choose a region you know well. We will classify every market in it,
share the output, and you can tell us where the model is wrong.
EPIC Intelligence · Client identity withheld